
Coinbase CEO Brian Armstrong has defended the exchange’s USDC rewards program as debate intensifies over whether crypto companies offering stablecoin rewards should face requirements similar to banks. Armstrong addressed the issue during a September 19 interview with MoneyRehabPodcast.
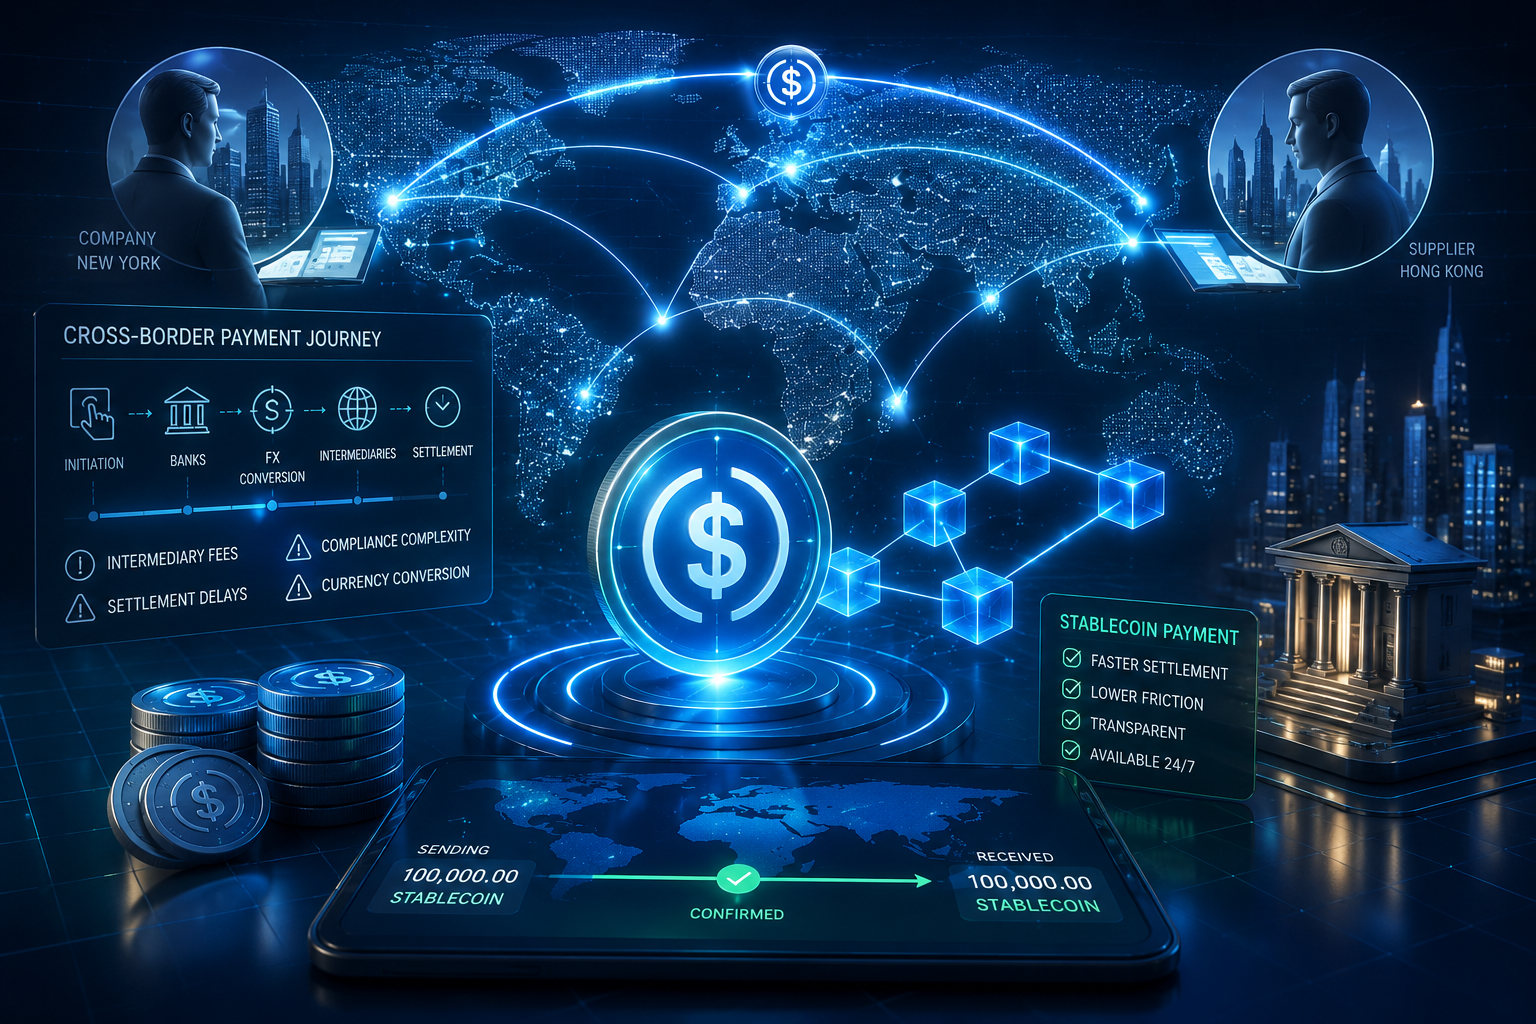
At the center of the discussion is a basic question: are rewards paid to USDC holders economically equivalent to interest paid on a bank deposit? Armstrong argued that the two arrangements are legally and structurally different, pointing to the way stablecoins are backed and how Coinbase generates returns from the assets associated with the ecosystem.
Armstrong said USDC rewards can pass through part of the returns generated from short-term U.S. Treasury assets. Coinbase’s current documentation, however, describes its USDC Rewards program as a loyalty program funded by Coinbase and says the company does not use or lend customers’ USDC without their instruction.
Armstrong Draws a Line Between USDC and Bank Deposits
The distinction matters because USDC is not a bank deposit. Coinbase states that USDC balances held on its platform are not deposit accounts and are not covered by FDIC or SIPC insurance. The exchange also says USDC is fully backed by cash and short-dated U.S. Treasuries held with regulated financial institutions.
Armstrong emphasized that Coinbase does not issue USDC. The stablecoin is operated by Circle, while Coinbase provides services around the asset. Coinbase’s institutional terms likewise state that the company is not the issuer of USDC and does not hold the reserves backing the stablecoin.
Related: Coinbase CEO Says Crypto Gets Regulatory Clarity With or Without CLARITY Act
He also pointed to the absence of fractional-reserve lending as a key difference between stablecoin infrastructure and traditional banking. Under the U.S. stablecoin framework, issuers must maintain reserves on at least a one-to-one basis against outstanding stablecoins, with permitted reserves including dollars and certain short-term Treasury assets.
That structure has become central to the political and regulatory argument over stablecoin rewards. Banking groups have raised concerns that attractive rewards could encourage consumers to move money away from bank deposits, potentially affecting the funding base banks use for lending.
The White House has previously acknowledged that concern in its analysis of stablecoin yield restrictions. Its research noted that the GENIUS Act prohibits stablecoin issuers from offering interest or yield directly to holders, while also highlighting questions around affiliate and third-party arrangements that could provide returns.
Banking Rules Become the Bigger Battle
Armstrong’s position is that applying bank-style capital and liquidity requirements to Coinbase because it offers rewards on USDC would fail to account for the structural differences between an exchange, a stablecoin issuer and a regulated bank.
Banks operate with balance sheets built around deposits, loans and other assets, while stablecoin arrangements generally depend on reserves designed to maintain the token’s dollar peg. Coinbase’s own terms also warn that stablecoin services are not the same as bank deposits and carry different market, liquidity, operational and regulatory risks.
Related: Apple and Google Hire Stablecoin Experts as Big Tech Explores Blockchain Payments
Armstrong also criticized major banks, arguing that some have sought government intervention to limit competition from crypto companies. That is his characterization of the banking industry’s position and reflects the broader conflict between traditional financial institutions and digital-asset companies over stablecoin regulation.
The dispute has become particularly important as U.S. lawmakers debate how stablecoins should interact with the traditional financial system. The GENIUS Act established a federal framework for payment stablecoins, including reserve requirements and restrictions on direct issuer-paid yield, but the treatment of rewards offered through exchanges and affiliates
About The Author