Chainlink is expanding its institutional finance offering with Fulcrum, a solution designed to connect tokenized assets with financing markets across public and private blockchains. Announced on September 30, 2026, Chainlink Fulcrum aims to help financial institutions use tokenized securities as collateral without being restricted to the blockchain where those assets reside. The system separates the venue where a financing agreement is managed from the networks where cash and collateral are settled, supporting transactions around the clock.
The launch addresses a significant challenge for institutional tokenization: making digital representations of financial assets useful beyond issuance and ownership records. Chainlink cites a Citi estimate that approximately one-quarter of institutional collateral sits idle because of settlement cutoffs and operational friction, costing an average Tier 1 institution roughly $346 million in forgone annual revenue. Fulcrum is designed to reduce these inefficiencies by connecting collateral to financing opportunities across multiple networks and venues.
How Chainlink Fulcrum Connects Tokenized Assets to Financing
Fulcrum is built around repurchase agreements, commonly known as repos, and other collateralized financing arrangements. In a typical repo, one party provides securities as collateral in exchange for cash and agrees to repurchase those securities later at a predetermined price. Financial institutions use these transactions to obtain short-term funding, manage liquidity and earn returns on available capital.
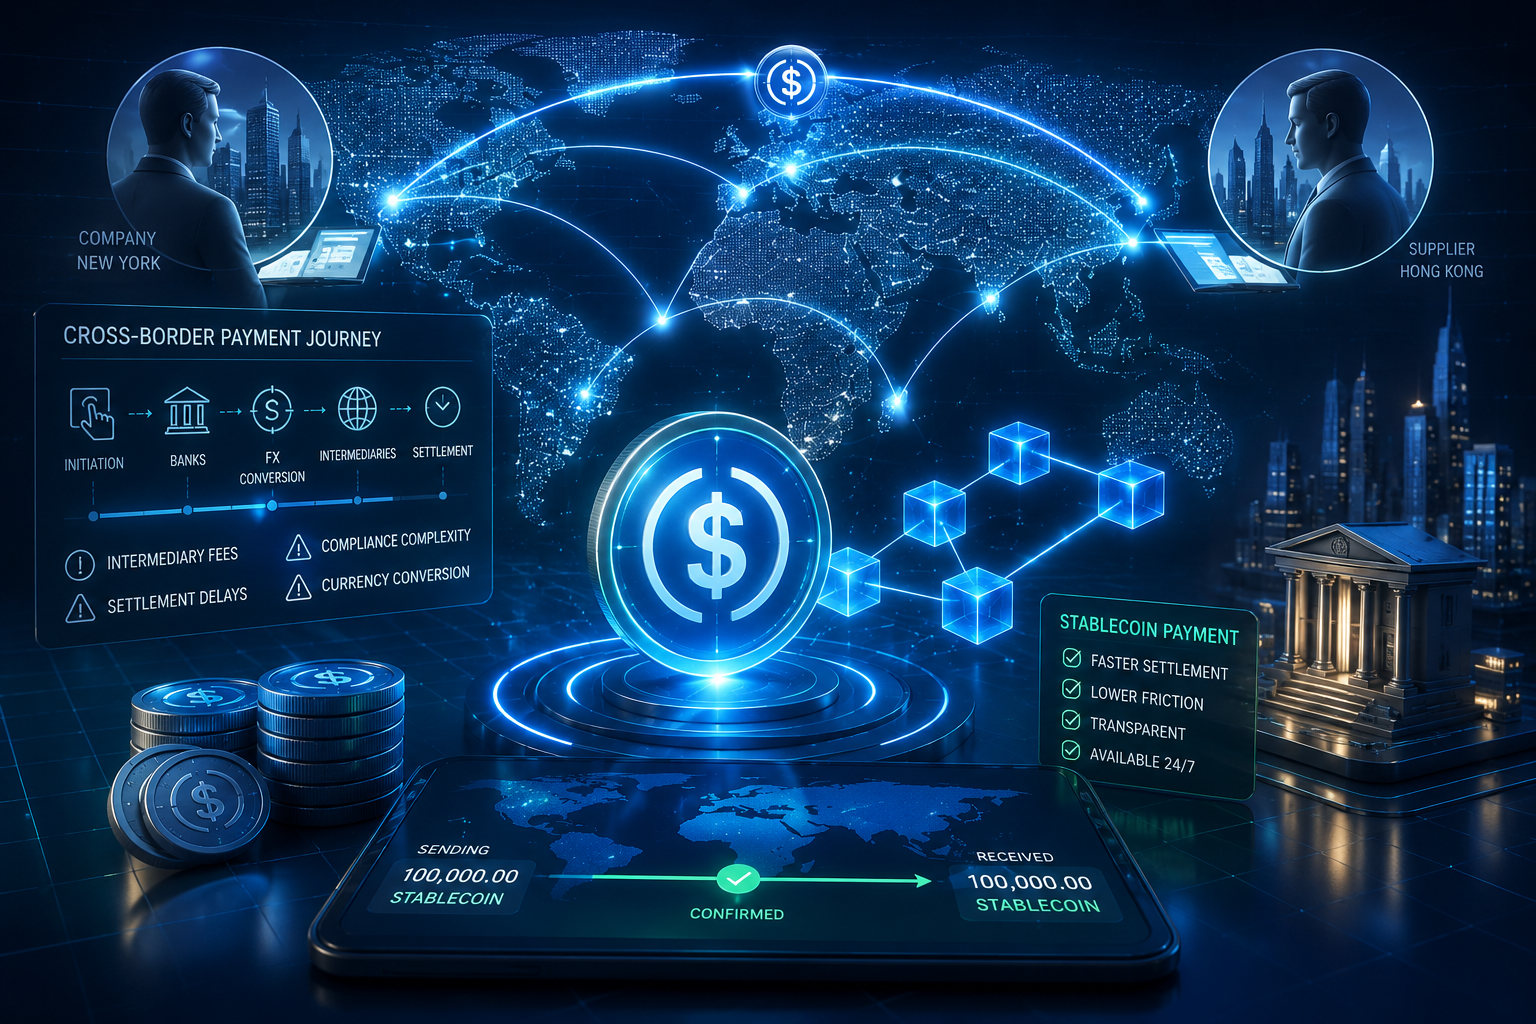
Tokenized assets introduce additional complexity when the collateral and cash operate on different blockchains. Institutions may face fragmented liquidity, disconnected systems and expensive custom integrations. Fulcrum is designed to coordinate these components through a reusable workflow, allowing counterparties to specify financing terms, eligible collateral, principal amounts, interest rates and applicable valuation discounts.
The solution combines several parts of Chainlink’s infrastructure. Its Runtime Environment (CRE) coordinates transaction workflows, while the Cross-Chain Interoperability Protocol (CCIP) enables communication and asset transfers between supported networks. Chainlink Data Streams supplies market data used to value collateral and calculate agreed-upon haircuts, which reduce the recognized collateral value to account for risk.
Together, these components are intended to support conditional settlement across chains. For example, a cash release on one network can depend on verification that the required collateral has been delivered on another. Chainlink says the system supports EVM and non-EVM networks covered by its CRE and CCIP infrastructure, although specific network support depends on the implementation.
Chainlink Fulcrum does not custody assets, act as a counterparty or operate its own trading venue. Instead, financing agreements are executed between participants and governed through venues integrated with the solution. This distinction means that transaction execution, contractual terms and venue-specific risks remain important considerations for participating institutions.
Why 24/7 Collateral Financing Matters to Institutions
Traditional financial markets operate within defined trading and settlement schedules, but digital asset markets function continuously. When collateral cannot be mobilized outside conventional business hours, institutions may need to hold additional liquidity or delay financing decisions. Fulcrum aims to make eligible assets usable across financing venues even when traditional markets are closed, potentially supporting intraday transactions, weekend funding and faster responses to changing exposures.
The solution also supports cross-margining and automated collateral monitoring as part of the broader financing workflow. Market data can help institutions track whether collateral remains sufficient relative to outstanding obligations. Depending on the terms established by counterparties, automated processes may support margin calls or liquidations when collateral values fall below agreed thresholds. These mechanisms can improve operational responsiveness, but they cannot eliminate market volatility or counterparty risk.
The ability to borrow against tokenized securities without selling them could be particularly relevant to asset managers and other institutions seeking liquidity while maintaining exposure to their investments. Lenders may gain opportunities to deploy cash against eligible collateral, while custodians and prime brokers could use standardized workflows to connect clients with financing markets. Corporate treasuries may also find applications in secured transactions involving otherwise idle cash.
Chainlink says Fulcrum is being integrated with leading traditional finance environments and existing venues, allowing participants to compare financing terms and select where agreements are executed. The company also describes its work with the Depository Trust & Clearing Corporation (DTCC) as a demonstration of cross-chain institutional financing at Sibos 2026. Wider availability and adoption will depend on completed integrations, institutional participation and the requirements of individual markets.
For the tokenization sector, the launch highlights a shift from issuing blockchain-based representations of assets toward making those assets usable in financial operations. Tokenized securities become more functional when institutions can finance them, manage collateral across networks and settle transactions without relying on isolated systems.
Fulcrum’s longer-term impact will depend on whether it attracts sufficient liquidity and delivers measurable improvements in financing costs and capital efficiency. Chainlink has outlined an infrastructure approach for connecting assets and financing venues across blockchains, but the scale of its benefits will need to be demonstrated through real-world institutional usage.
About The Author