
Blockchain adoption is not the same as token demand. As crypto moves into payments, financial infrastructure and real-world applications, investors face a difficult question: who actually captures the value?
The crypto industry has spent years promising that mainstream adoption will reward the people who bought its tokens early. Banks will use blockchain. Companies will tokenize assets. Payments will move on-chain. Developers will build applications that traditional financial systems cannot easily replicate.
Suppose all of it happens.
Suppose blockchain transactions multiply, financial institutions adopt the technology, stablecoins become more widely used and tokenized assets grow into a substantial market. Would the average altcoin investor necessarily make money?
No. And that distinction could determine which crypto projects survive the next phase of the industry — and which leave their token holders behind.
A successful technology does not automatically produce a successful investment. A profitable business does not automatically produce a valuable token. Crypto investors who fail to distinguish these outcomes risk backing the right industry while owning the wrong asset.
The industry has confused adoption with value
For years, crypto projects have sold investors a relatively simple proposition: build useful technology, attract users and the token should appreciate.
The logic sounds reasonable. Greater demand for a network should increase demand for its native asset, particularly when that asset is required for transactions, staking, collateral or access to network resources.
But the relationship is not automatic. It depends on the economics of the particular network.
A company can use blockchain infrastructure without purchasing a project’s token as a long-term investment. An application can generate revenue while directing most of that revenue to operators, validators, liquidity providers or a corporate treasury. A network can process millions of transactions while charging so little per transaction that its revenue remains modest.
Even when a token is necessary to use a network, the amount users need to hold may be small. Tokens can circulate rapidly, and demand for transaction balances does not necessarily translate into sustained demand for investment holdings.
This is the gap that many bullish narratives overlook: adoption creates potential economic value, but token design determines how much of that value reaches token holders.
The distinction is becoming harder to ignore as crypto expands beyond speculation into financial infrastructure.
More blockchain activity does not always mean more money
Ethereum provides a useful illustration of the problem.
In its July 2026 Half-Year 2026: On-Chain Markets report, Binance Research described a sharp divergence between Ethereum’s activity and its revenue outlook. Following an increase in the network’s gas limit to approximately 60 million, average gas prices were about 75% lower than in 2025, while transaction counts had risen around 50%. Despite the increase in transactions, Binance Research projected that Ethereum’s chain revenue would decline 53% over the full year.
These are figures and a forecast from the report, not a verified final result for 2026. But the economic question they raise is important.
Lower fees can make a network more attractive to users and developers. Higher transaction capacity can support applications that would otherwise be too expensive to operate. Those are genuine technological and competitive advantages.
However, when the price paid per transaction falls substantially, activity can rise without producing a corresponding increase in network revenue.
That does not automatically make ETH a poor investment. Ethereum’s economics involve staking, monetary issuance, fee burning, settlement demand and other factors beyond immediate transaction revenue. The point is that transaction growth alone cannot establish whether the asset is becoming more valuable.
Investors must examine the entire economic model, not select whichever metric supports their preferred conclusion.
The stablecoin problem: blockchain adoption without equivalent token demand
Stablecoins expose the same contradiction from another direction.
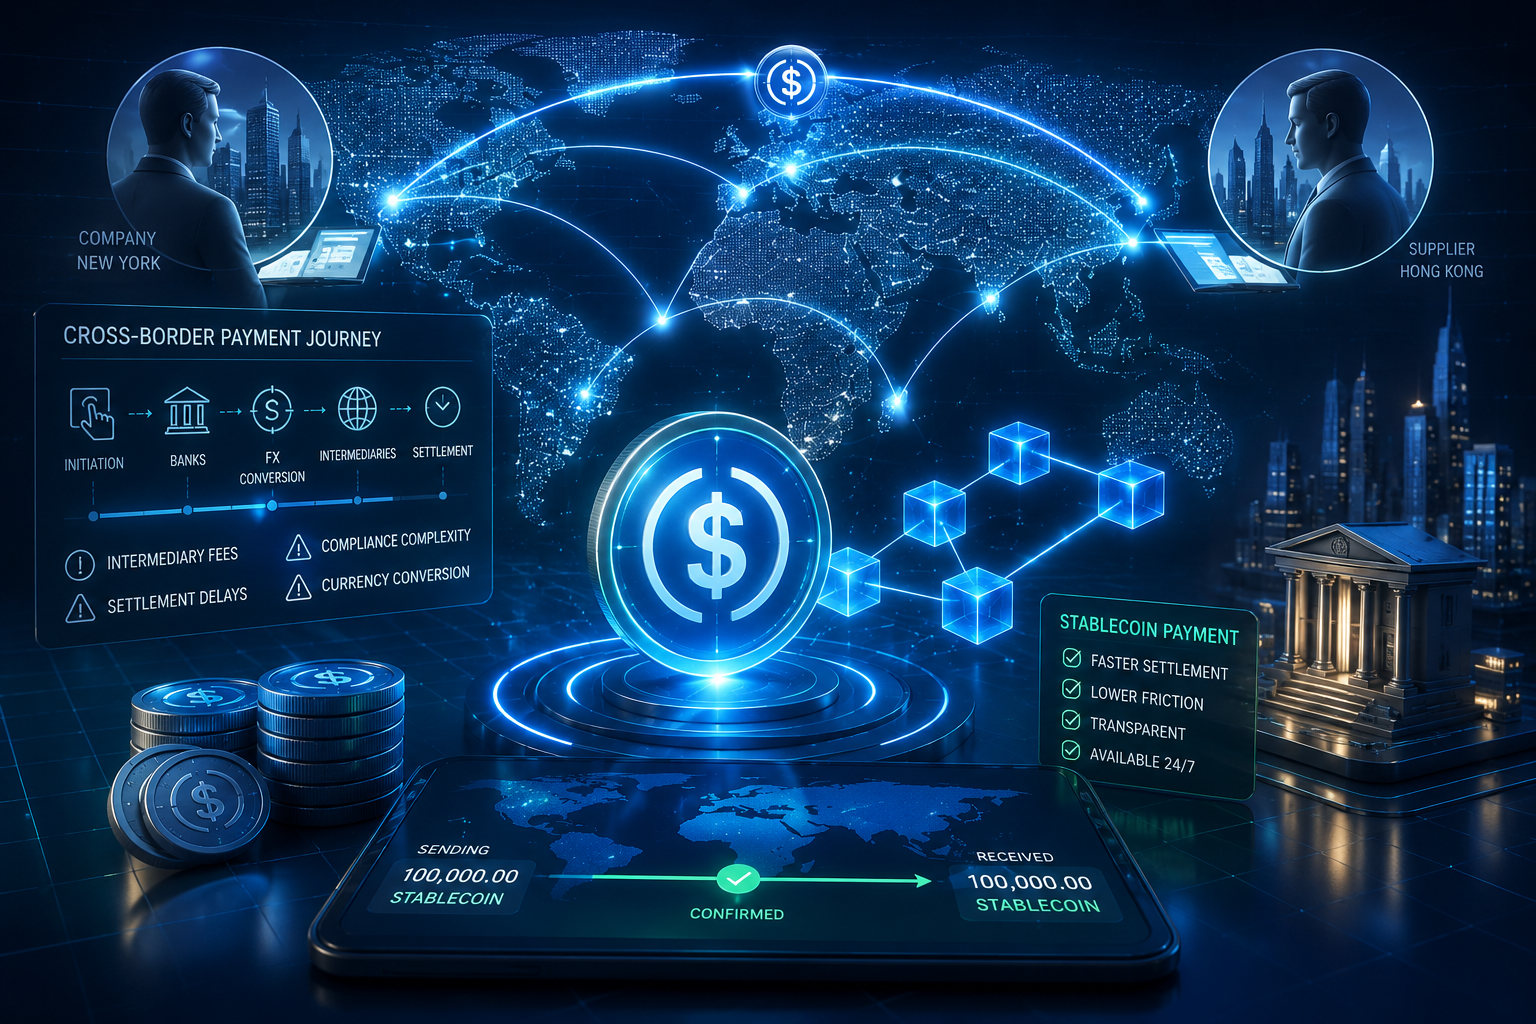
A business can use a dollar-backed stablecoin to settle payments, transfer funds internationally or move money between financial platforms. A trading platform can depend on stablecoin liquidity. A payment company can build products around blockchain settlement.
These developments can generate substantial activity for the infrastructure supporting them.
But the economic beneficiaries are not necessarily the holders of every token associated with that infrastructure.
The stablecoin issuer may earn income from reserve assets. A payment company may charge customers for its services. An exchange may earn trading fees. A blockchain may collect transaction fees. A native token may benefit from some of this activity — or capture relatively little of it.
Consider a hypothetical company that processes $1 billion in stablecoin payments through a blockchain. That figure sounds impressive, but it does not tell us how much revenue the company earns, how much the network collects, how much demand the native token receives or whether the token captures any lasting economic benefit.
Transaction volume is not revenue. Revenue is not profit. And neither automatically translates into token-holder returns.
Investors who confuse these measures can end up celebrating adoption that has little direct bearing on the asset they own.
Tokenized assets could expose the same weakness
The tokenization of real-world assets is often presented as a major opportunity for blockchain networks. Financial institutions can use digital tokens to represent claims on assets such as government securities, funds and other financial instruments.
The opportunity is real, but its implications for individual cryptocurrencies remain uncertain.
Imagine a financial institution tokenizing billions of dollars in assets. The assets might be issued on a public blockchain, a permissioned network or infrastructure that combines several systems. The institution could pay service providers, custodians and technology companies while using a blockchain’s native token only for limited transaction fees.
In that scenario, tokenization succeeds as a business model. The infrastructure becomes more useful. Investors in the institution or service providers might benefit.
Yet holders of a particular cryptocurrency would still need evidence that the new activity creates meaningful demand for their asset.
Which token must be acquired? Who receives the fees? Is the token required as collateral? Does usage generate burns or other mechanisms that affect supply? Could the same service operate on another network with minimal switching costs?
These are not minor technical questions. They determine whether a broad industry trend translates into a credible investment thesis for a specific token.
The mistake is assuming that because blockchain is used, every cryptocurrency connected to blockchain will benefit.
The tokenomics trap: when growth creates more selling pressure
Even projects with real users and growing revenue can struggle if their token economics work against existing holders.
Consider a hypothetical network whose applications and commercial activity are expanding. At the same time, the network issues new tokens to fund incentives, reward participants and release allocations to early investors.
If the additional supply grows faster than sustained demand for the token, the price can remain under pressure despite improving fundamentals.
That outcome is not guaranteed. New issuance can help bootstrap a network, incentivize useful activity and support long-term development. Unlocks do not mean that every recipient will sell.
But the supply side cannot be ignored.
Investors need to know how much of the token is circulating, how much remains locked, when new tokens can enter the market and what economic benefits justify holding the asset. They must also distinguish between staking rewards funded by external revenue and rewards funded largely through new issuance.
A headline annual staking yield can look attractive while the underlying token loses purchasing power through dilution.
Similarly, a token burn may reduce supply without being large enough to offset issuance. A buyback may support demand without guaranteeing that the token’s market value will increase.
The relevant question is not whether a project has a burn, staking programme or revenue stream. It is whether the combined economics create durable value for holders relative to the price they pay.
Four questions that separate a promising project from a promising investment
The next generation of altcoin analysis should be more demanding than a checklist of partnerships, roadmaps and transaction counts.
1. Who pays?
Identify the actual customer and what they pay for. Is the network serving businesses, developers, traders or speculative users? Are payments recurring, and are customers paying from genuine demand rather than temporary incentives?
2. Who earns?
Trace the money. Determine what goes to the network, applications, validators, liquidity providers, foundations and other participants. Where possible, distinguish gross fees, protocol revenue, operating costs and profits.
3. Why does the token need to exist?
Establish whether users must acquire or hold the token, whether it is needed for security or collateral, and whether its role becomes more economically important as the network grows. A governance function or a place on an exchange is not, by itself, proof of meaningful value capture.
4. Can demand outrun supply?
Examine issuance, vesting, unlocks, treasury allocations and ownership concentration alongside the drivers of token demand. A network can grow while its token struggles if the supply and demand dynamics remain unfavourable.
These questions will not predict every price movement. Crypto remains exposed to liquidity cycles, regulation, competition, speculation and macroeconomic shocks. But they provide a more rigorous foundation than assuming that every successful blockchain must produce a successful token.
The winners may not be the tokens investors expect
The next phase of crypto could reward projects that solve real problems, but the beneficiaries may be distributed unevenly.
Some networks could capture value through fees, security requirements or other mechanisms tied directly to their native assets. Some applications could generate attractive businesses while their governance tokens capture little of the economic upside. Some infrastructure providers could benefit from adoption without requiring investors to hold a speculative cryptocurrency at all.
Others may create genuine utility but struggle to sustain demand after incentives fade or competitors offer cheaper alternatives.
This is why investors should stop evaluating altcoins as if they were interchangeable bets on the growth of blockchain.
A cryptocurrency is not an equity share in every company using its network. It does not automatically confer a right to protocol revenue, and owning a token does not necessarily mean owning a claim on the underlying business.
The rights, supply rules and economic mechanisms depend on the specific asset. Those details matter more than the general promise of adoption.
Altcoin investors need to change the question
The easiest crypto narrative to sell is that the industry is growing and the tokens must eventually follow.
The harder question is which tokens are positioned to benefit economically from that growth — and whether the market has already priced in those benefits.
That requires examining the relationship between technology, actual users, revenue, token demand and supply. It means questioning impressive partnership announcements, distinguishing network activity from economic performance, and acknowledging when the evidence is incomplete.
It also means accepting an uncomfortable possibility: a project can succeed on its own terms while its token remains a disappointing investment.
That is not necessarily a failure of blockchain technology. It may be a failure of token design, valuation or investor expectations.
The next crypto winners will not simply be the projects that attract the most adoption. They will be the projects whose tokens have a defensible economic reason to benefit from it.
For investors, that is the difference between betting on the future of blockchain and understanding what they are actually buying.
About The Author